Finding clarity when markets refuse to behave

We began where classical models ended — in the space where probabilities themselves become uncertain, and where standard tools quietly fail.

Reach our team

Build frameworks that survive unknown unknowns

When you cannot trust the distribution, you need a decision architecture that still functions. We help you construct planning systems that remain coherent even when the underlying model is misspecified, turning ambiguity from a source of paralysis into a manageable input.

Explore planning

The people who built this language

Researchers, practitioners, and translators who moved ambiguity robust asset pricing from seminar rooms into working tools. Each brings a different lens — econometrics, decision theory, institutional practice — but shares one conviction: uncertainty about probabilities is too important to leave to one discipline alone.

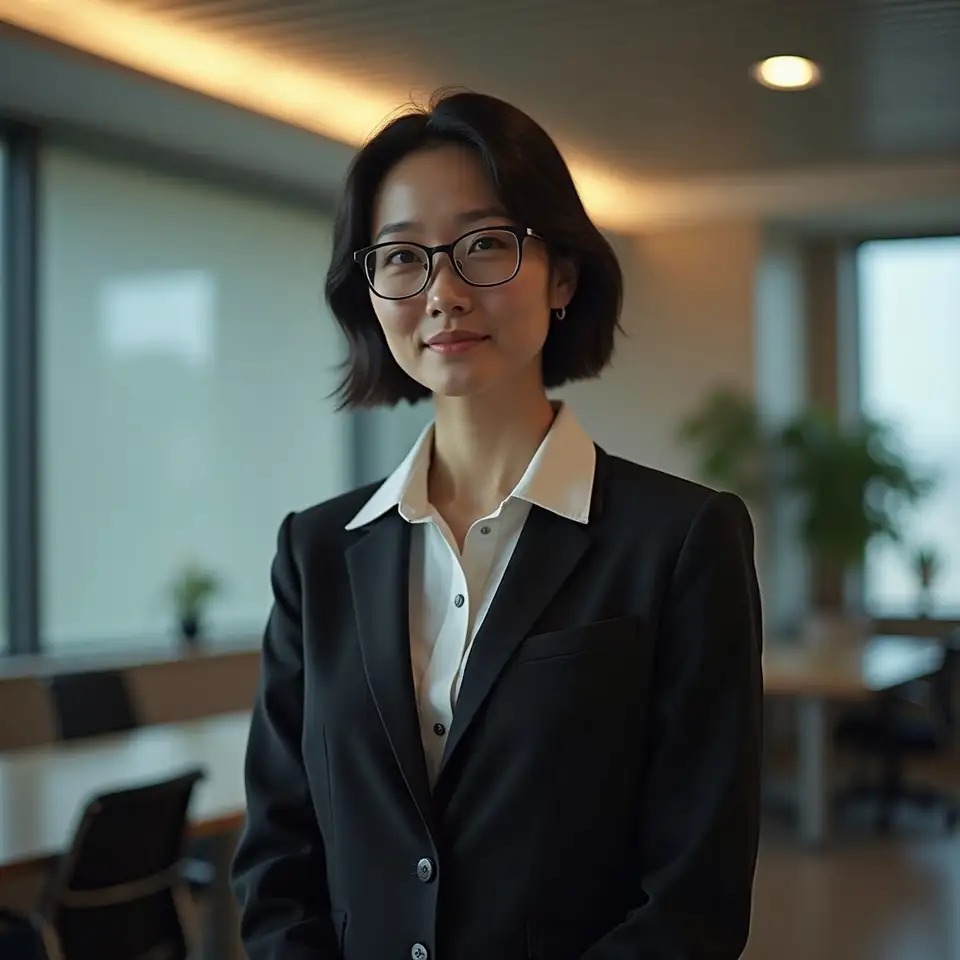
  1. Dr. Eleanor Vance-Chen

    Dr. Eleanor Vance-Chen

    Founding Research Director

    Eleanor spent fifteen years watching elegant pricing models collapse when assumptions frayed. Her work on robust control under Knightian uncertainty bridges econometric theory with the practical demands of institutional analytics.

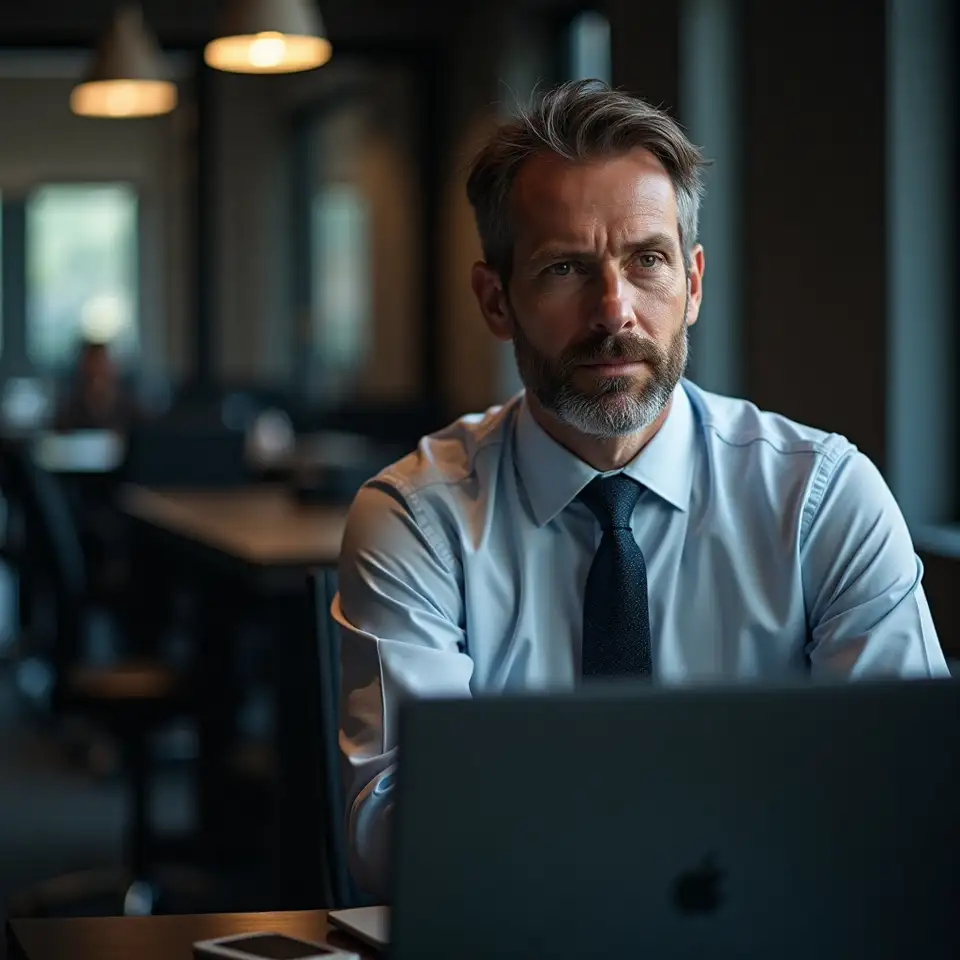
  2. Marcus O'Brien-Finn

    Marcus O'Brien-Finn

    Lead Methodologist

    Marcus came to ambiguity robust frameworks after a decade in policy analysis, where the worst errors always traced back to overconfidence in assumed distributions. He now designs the three-step consultation that translates theory into client workflow.

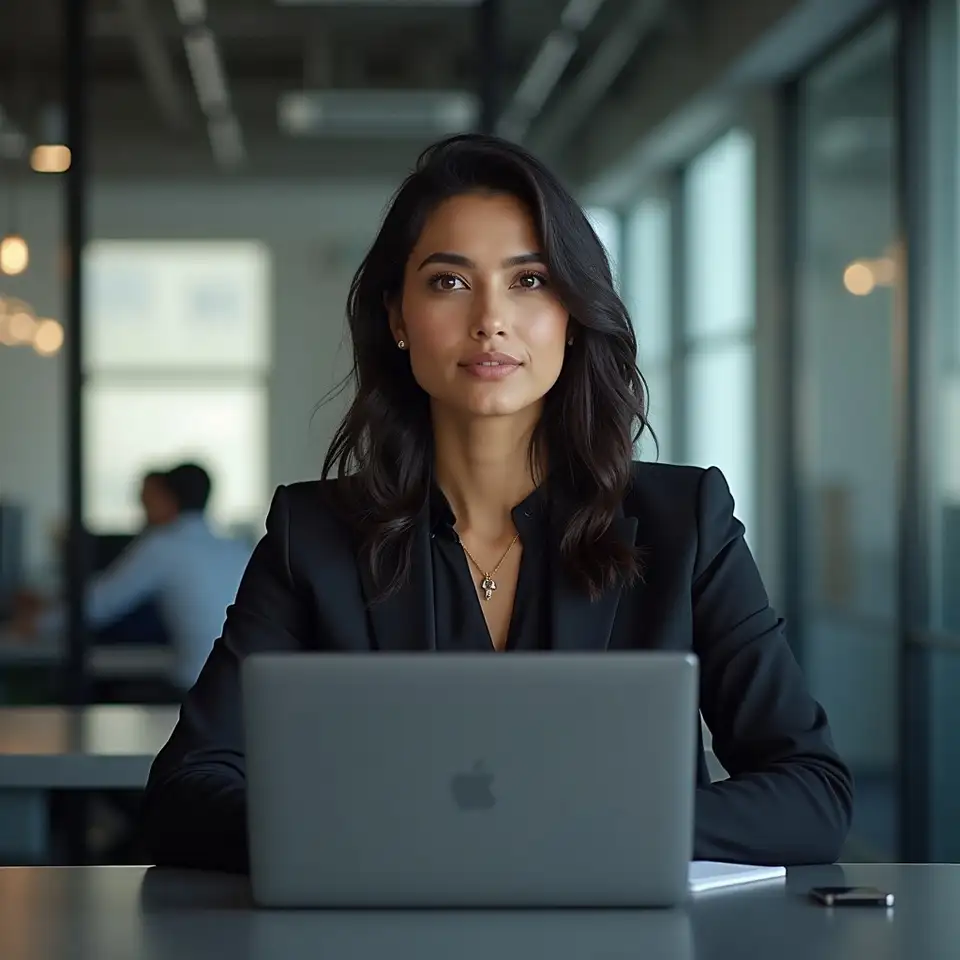
  3. Dr. Aisha Patel-Ramirez

    Dr. Aisha Patel-Ramirez

    Senior Quantitative Researcher

    Aisha's research focuses on model misspecification in dynamic asset pricing. She builds the stress-testing layers that let practitioners see how fragile their conclusions are before markets do the same.

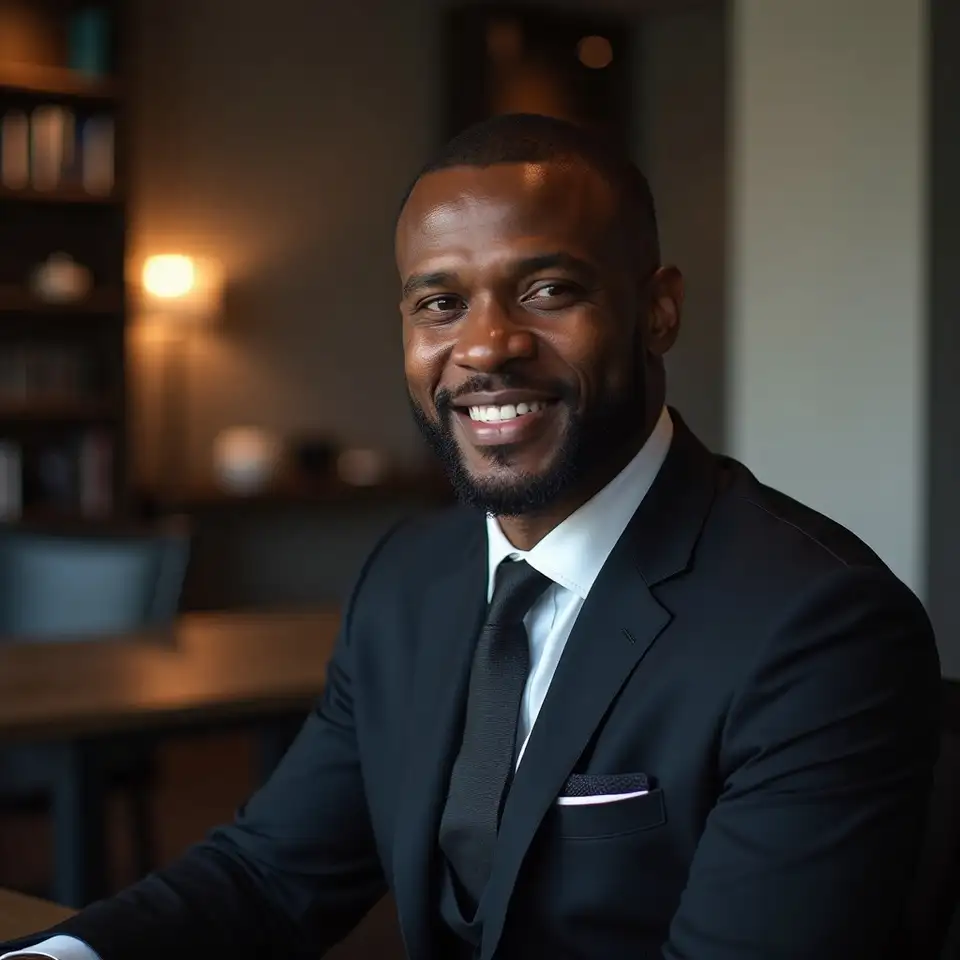
  4. James Okonkwo-Doyle

    James Okonkwo-Doyle

    Head of Institutional Partnerships

    James translates between academic rigor and organizational reality. He ensures that every framework we develop can survive the procurement, compliance, and cultural hurdles of real institutions.

  5. Dr. Yuki Tanaka-Morrison

    Dr. Yuki Tanaka-Morrison

    Robust Control Specialist

    Yuki's background in control theory and stochastic processes informs the algorithmic core of our smart tools. She is obsessed with making robust optimization run fast enough for daily decisions.

  6. Dr. Samuel Osei-Boateng

    Dr. Samuel Osei-Boateng

    Senior Decision Theorist

    Samuel studies how humans actually reason under ambiguity, not how textbooks say they should. His behavioral insights keep our frameworks grounded in cognitive reality rather than idealized rationality.

Recognition for advancing ambiguity robust thinking

1

Honored for developing accessible frameworks that translate ambiguity aversion theory into practical tools for institutional analysts and independent researchers alike.

2024
2

Recognized for rigorous empirical work demonstrating how robust control methods improve portfolio resilience during periods of distributional ambiguity.

2023
3

Awarded for pioneering approaches that integrate ambiguity robustness into standard valuation workflows without requiring specialized computational infrastructure.

2023
4

Celebrated for bridging econometrics, decision theory, and institutional practice to create methodologies usable across academic and professional boundaries.

2022
5

Acknowledged for curriculum design that makes robust control and model uncertainty accessible to practitioners without doctoral training in mathematics.

2021
6

Awarded for foundational work on Knightian uncertainty in continuous-time models, establishing new analytical pathways for robust pricing theory.

2019

From research insight to working practice

A short history of how a small group of researchers turned a theoretical problem into practical tools.

2017

The initial insight

A series of research papers identified systematic failures in expected utility models during periods of market ambiguity. The authors realized the problem was not the models themselves, but the assumption that agents know the true probability distribution.

Research Publications
2019

First institutional collaboration

A central bank research department invited the team to test robust control methods on real macroeconomic data. The collaboration proved the theory could survive contact with messy, incomplete datasets and impatient policy deadlines.

Partnership Validation
2021

Platform prototype launched

The first version of the analytical platform went live, designed specifically for practitioners who needed ambiguity robust tools but lacked the computational infrastructure to build them from scratch.

Product Launch
2023

Curriculum opened to practitioners

Recognizing that tools alone were insufficient, the team developed structured guidance for applying robust frameworks in daily analytical work, tested with a cohort of institutional researchers.

Guidance Practice
2025

Expanded institutional network

Partnerships with research departments, policy institutions, and independent analytics firms created a feedback loop that continuously refines the frameworks against real-world complexity.

Growth Network
Seven years of building

If you are wrestling with model uncertainty and tired of pretending you know more than you do, we would like to hear from you. No performance, no pitch — just a conversation about what robust decision-making could look like in your context.

Say hello